Long Term Care Annuity: Is It Right for Your Retirement?
A long-term care annuity is a hybrid financial product that combines a traditional annuity with long-term care benefits, converting a lump-sum premium into both a guaranteed income stream and a pool of funds reserved for care expenses. It tends to suit retirees who have a sizable asset they want to reposition, prefer locked premiums over ongoing insurance payments, and want any unused benefit to pass to heirs rather than disappear. Three signals that you’re a good candidate: you have $75,000 or more in a non-qualified account or CD sitting idle, you want care coverage without the “use it or lose it” sting of standalone insurance, and you can tolerate limited liquidity for several years.
Before you go deeper, here are the three fastest next steps:
Estimate your coverage need: Find your local monthly nursing home or assisted living cost, then divide your likely premium by that figure to see how many months of raw coverage you’d have before any multiplier.
Compare illustrations from at least two carriers: Multipliers, elimination periods, and inflation riders vary enough between contracts that a side-by-side illustration is the only reliable way to compare.
Ask these three questions upfront: What triggers benefits (ADL count, cognitive impairment)? Is the inflation rider compound or simple? What is the surrender schedule and free-withdrawal provision?
Key Takeaways
A long-term care annuity converts a single lump-sum premium into both a care benefit pool and a death benefit, making it best suited for retirees who want to reposition idle assets rather than pay ongoing insurance premiums.
Point | Details |
Multiplier drives coverage depth | A 2.5x multiplier on a $100,000 premium creates a $250,000 benefit pool; age and health determine your actual multiple. |
Monthly cap matters more than multiplier | Divide the benefit pool by your local monthly care cost to find real months of coverage, not just the ratio. |
Compound inflation rider is critical | A compound rider materially improves long-term benefit value; skipping it to lower cost is a common and costly trade-off. |
Tax and Medicaid effects require advice | Qualifying LTC payouts can be tax-favored under the Pension Protection Act, but funding source and contract structure determine actual treatment. |
East Two West simplifies comparison | East Two West provides side-by-side carrier illustrations with no sales pressure, online or by consultation. |
Table of Contents
What is a long-term care annuity, and how does it differ from a standard annuity?
What are the pros and cons of using an annuity for long-term care?
How does an LTC annuity compare with standalone LTC insurance and hybrid life products?
How to estimate whether an LTC annuity covers enough — worked example
Common pitfalls and red flags when shopping for LTC annuities
An editorial perspective on LTC annuities and what most buyers miss
Get a fast, no-pressure LTC annuity quote through East Two West
What is a long-term care annuity, and how does it differ from a standard annuity?
A standard annuity converts a premium into an income stream, full stop. A long-term care annuity does that and more: it layers a care benefit on top, so that if you need help with daily activities, the contract pays out at an accelerated or enhanced rate to cover those costs. The industry also calls these products “hybrid annuities” or “asset-based long-term care” products, and that second term is worth knowing because it’s the phrase you’ll see on carrier illustrations and in regulatory filings.
The structural difference from standalone long-term care insurance is equally important. With a traditional LTC insurance policy, you pay annual premiums and receive benefits only if you need care. If you never need care, the premiums are gone. With an LTC annuity, the underlying account value belongs to you or your heirs regardless of whether you ever trigger the care benefit. That “use it or leave it” feature is the core appeal.
The NAIC shopper’s guide to long-term care confirms that some annuity contracts now offer long-term care riders or extensions of benefits, and that adding these features can change surrender charges, death benefits, and tax treatment. That’s not a minor footnote. It means the product you’re evaluating is materially different from a plain deferred annuity, and the contract language deserves careful review.
How LTC annuities compare at a glance:
Feature | Standard annuity | Standalone LTC insurance | LTC annuity (hybrid) |
Premium structure | Lump sum or periodic | Annual premiums (can increase) | Typically single lump sum |
Benefit if no care needed | Income payments or death benefit | Nothing (premiums forfeited) | Account value to heirs |
Care benefit depth | None | High daily/monthly limits | Moderate (multiplier-based) |
Premium stability | Fixed at purchase | Subject to rate increases | Fixed at purchase |
Underwriting | Minimal | Full medical underwriting | Simplified to moderate |
Benefit triggers across most contracts follow the same federal standard: inability to perform at least two of six activities of daily living (ADLs) — bathing, dressing, eating, continence, toileting, and transferring — or a diagnosis of severe cognitive impairment. These definitions align with the criteria the IRS uses to determine whether LTC benefits qualify for favorable tax treatment.
What types of LTC annuities are available?
The product landscape breaks into three main forms, and the right one depends heavily on when you need coverage and how much flexibility you want.
Immediate LTC annuities
A single-premium immediate annuity (SPIA) with LTC features starts paying income soon after purchase. Some contracts allow an enhanced payout if the annuitant qualifies for care, effectively doubling or tripling the monthly income during a care period. These products are worth considering when you’re already in your late 70s or early 80s, or when a family member needs care now and you need to convert an asset quickly. Underwriting is typically simplified because the income stream starts immediately, but the trade-off is that the benefit pool is smaller relative to what a younger buyer could build with a deferred product.
Deferred hybrid annuities
This is the most common form. You deposit a single premium, and the contract creates two pools: the account value (your money, growing at a declared or indexed rate) and the benefit base (a larger pool, often two to three times the premium, reserved for LTC expenses). You don’t touch the benefit base unless you trigger the care criteria. Fidelity notes that hybrid LTC annuities commonly create a benefit pool worth approximately two to three times the initial premium, with gains used for qualifying LTC expenses receiving tax-favored treatment. The waiting period before benefits become available varies by contract, often measured in weeks or months.
LTC riders on income annuities
Rather than a purpose-built hybrid, some buyers add an LTC rider to an existing or new income annuity. The most common form is a “doubler” or “tripler” rider: if you qualify for care, your monthly income payment doubles or triples for a defined period. My Annuity Doctor explains three primary annuity approaches to LTC funding, including these income-enhancement riders, and notes that the Pension Protection Act established the tax framework that makes qualifying payouts favorable. The catch with doublers is that the enhanced income has a cap, usually two to five years, so they work best as a supplement rather than a primary care funding strategy.
Eligibility notes: Most carriers accept applicants within a broad age range, with younger ages typically receiving better multipliers. Full underwriting applies to most deferred hybrid products; simplified underwriting is more common on rider-based products. Pre-existing conditions, cognitive decline, and recent hospitalizations are common disqualifiers.
Pro Tip: *Apply before age 70 if your health allows. Multipliers drop noticeably as you age, and some carriers close underwriting entirely above age 75.
How do LTC annuity mechanics actually work?
Understanding the moving parts before you see an illustration prevents you from being dazzled by a large benefit-pool number that doesn’t actually cover your local care costs.
The benefit base and multiplier
The multiplier is the ratio of your LTC benefit pool to your initial premium. That pool is drawn down as you receive monthly care payments. Younger, healthier buyers typically receive higher multipliers than older applicants, because the carrier is pricing the longer period before a claim is likely. The exact multiple is highly sensitive to age and underwriting, so the number on your illustration is specific to you, not a market-wide standard.
Elimination periods
Think of the elimination period as a time-based deductible. Most contracts require 60 to 90 days of qualifying care before the LTC benefit kicks in. During that window, you pay out of pocket. A longer elimination period lowers the cost of the rider or increases the multiplier the carrier will offer, but it also means you need liquid assets to cover that initial stretch. An elimination period measured in months at typical monthly care costs results in a substantial out-of-pocket expense before benefits begin.
Payout models
Three structures are common:
Reimbursement model: You submit receipts for qualifying care expenses, and the carrier reimburses up to the monthly cap. Unused monthly amounts may roll over or be forfeited depending on the contract.
Cash/indemnity model: The carrier pays the monthly benefit directly to you once you qualify, regardless of actual expenses. More flexible, but often carries a higher premium or lower multiplier.
Enhanced income (doubler/tripler): Your base annuity income multiplies during a care period. Simple to understand, but the benefit duration is usually capped at two to five years.
Inflation protection
This is where most buyers underestimate the long-term math. A $6,000 monthly benefit today covers a lot less care in 15 years if it doesn’t grow. Simple inflation riders increase the benefit by a fixed dollar amount each year. Compound riders increase it by a percentage of the growing benefit, which means the gap between the two widens dramatically over time. Practitioners consistently flag compound inflation as one of the most consequential riders to evaluate, because it materially improves long-term purchasing power even though it raises the upfront cost. The LegalClarity overview of LTC annuity mechanics illustrates how compound inflation significantly improves long-term benefit value compared to simple growth over long periods.
Surrender charges and liquidity
If you need your money back in year three, you’ll pay a meaningful charge. That’s not a reason to avoid the product, but it is a reason to fund it only with money you genuinely don’t need liquid.
Key figure: Annuity.org’s analysis of LTC riders notes that adding an LTC rider typically reduces the base income payment in exchange for the potential care benefit, so buyers should model both the care scenario and the no-care scenario before committing.
Pro Tip: Request the carrier’s “non-forfeiture” provision details in writing. Some contracts include a reduced paid-up benefit if you stop paying or surrender early, which can preserve a portion of your LTC coverage even if you need to exit the contract.
What are the pros and cons of using an annuity for long-term care?
The honest answer is that LTC annuities are a strong fit for a specific buyer profile and a poor fit for others. The table below lays out the core trade-offs.
Pros | Cons |
Locked single premium, no future rate increases | Large upfront capital required (typically $50,000+) |
Unused benefit passes to heirs as death benefit | Limited liquidity during surrender period |
Tax-favored LTC payouts under qualifying rules | Total LTC coverage may be lower than a standalone policy |
Simplified underwriting vs. standalone LTC insurance | Multiplier shrinks with age and health decline |
Repositions idle assets rather than spending new money | Indexed-crediting complexity can obscure true returns |
No “use it or lose it” — account value preserved | Inflation rider adds cost; skipping it is a long-term risk |
When it works well: A 64-year-old with $150,000 in a non-qualified CD earning minimal interest repositions that money into a hybrid annuity. The premium is fixed, and she’s converted a low-yield asset into meaningful care protection without writing a new check every year.
When it doesn’t: A 72-year-old with moderate health issues who needs maximum daily benefit coverage for a potential five-plus-year nursing home stay will likely find that a standalone LTC policy (if he can still qualify) delivers more total benefit dollars per premium dollar.
The NAIC guidance and industry practitioners broadly agree that hybrid LTC annuities are a better fit for buyers prioritizing wealth preservation and legacy than for buyers who need maximum daily LTC reimbursement.
How does an LTC annuity compare with standalone LTC insurance and hybrid life products?
Feature | LTC annuity | Standalone LTC insurance | Hybrid life/LTC |
Premium structure | Single lump sum | Annual (can increase) | Single or limited pay |
Death benefit | Yes (account value) | No | Yes (life insurance face amount) |
Coverage depth | Moderate (multiplier-based) | High (daily/monthly limits) | Moderate to high |
Premium stability | Fixed | Subject to rate increases | Fixed |
Underwriting | Simplified to moderate | Full medical | Full medical |
Medicaid interaction | Can affect eligibility | Can affect eligibility | Can affect eligibility |
Liquidity | Limited (surrender schedule) | None (premiums spent) | Limited |
The ACL’s guidance on annuities for LTC funding describes both immediate and deferred structures and specifically warns that annuities can affect Medicaid eligibility, which is a point that applies across all three product types above.
Decision matrix:
Choose an LTC annuity if you have a lump sum to reposition, want premium certainty, and value the death benefit for heirs.
Choose standalone LTC insurance if you need the highest possible daily benefit and can qualify medically. For a deeper look at how standalone policies work, the complete LTC insurance buyer’s guide covers the full policy structure.
Choose a hybrid life/LTC product if life insurance is also a priority and you want a single contract to serve both needs.
The practical underwriting difference matters: standalone LTC insurance typically requires the most rigorous health screening, while LTC annuities use simplified or moderate underwriting. Buyers who have been declined for standalone LTC insurance sometimes qualify for an LTC annuity, making it a realistic fallback rather than just a preference.
What are the tax, estate, and Medicaid implications?
Tax treatment
The Pension Protection Act of 2006 established tax rules that allow qualifying LTC distributions from hybrid annuity contracts to be excluded from taxable income under certain conditions, provided the contract and distributions meet federal criteria. This is a meaningful advantage over drawing down a taxable account to pay for care. However, the tax treatment depends on whether the annuity was funded with pre-tax (qualified) or after-tax (non-qualified) money, and on the specific contract structure. The IRS private letter ruling 0919011 illustrates that distributions and exchanges in annuity/LTC situations can carry specific tax consequences, which is why personalized tax advice is not optional here.
A 1035 exchange — moving money from an existing annuity or life insurance policy into a new LTC annuity without triggering a taxable event — is a commonly used strategy. It works cleanly for non-qualified contracts but requires careful execution. Funding an LTC annuity from a traditional IRA or 401(k) is more complicated because those funds are pre-tax, and the distribution is taxable regardless of how it’s used. For a broader look at how annuities interact with retirement accounts, the Roth IRA vs. annuity comparison covers the key trade-offs.
Pro Tip: A 1035 exchange from a low-basis non-qualified annuity into an LTC hybrid is one of the cleanest funding moves available. You avoid the taxable gain on the old contract and immediately reposition the full value into a care benefit pool. Confirm the exchange qualifies under current IRS rules with your tax advisor before initiating the transfer.
Medicaid eligibility
Annuities can complicate Medicaid eligibility in ways that catch buyers off guard. Medicaid counts certain annuities as countable assets, which can delay or disqualify eligibility for nursing home coverage. The SSA’s long-term care FAQ reinforces that Medicare does not cover most long-term care, and Medicaid coverage depends on strict asset eligibility rules. Partnership-qualified LTC policies (available in most states) offer dollar-for-dollar asset protection against Medicaid spend-down, but not all LTC annuities carry partnership qualification. Verify this with your state’s Medicaid office before assuming protection.
Estate planning effects
The death benefit on an LTC annuity passes to named beneficiaries, typically the remaining account value or a guaranteed minimum. This is the “use it or leave it” feature that distinguishes the product from standalone insurance. The beneficiary designation controls who receives the remaining value, so keeping it current matters as much as it does on any life insurance policy.
Key point: LTC annuity death benefits generally avoid probate when a beneficiary is named, but they may still be included in the taxable estate for federal estate tax purposes. Consult an estate planning attorney if your estate exceeds the federal exemption threshold.
How to estimate whether an LTC annuity covers enough — worked example
The multiplier number alone tells you nothing useful. What matters is whether the benefit pool, drawn down at your local care cost, lasts long enough to matter.
Step-by-step calculation:
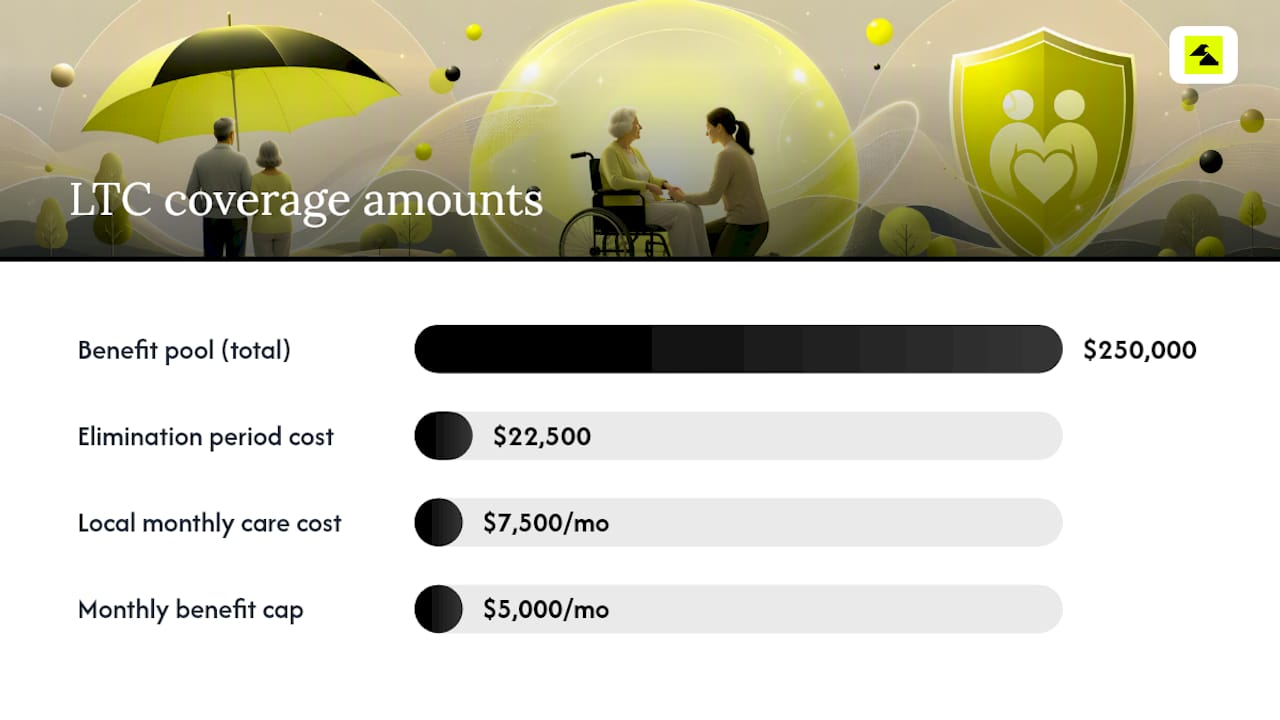
Identify your local monthly care cost. The ACL’s cost-of-care data provides regional benchmarks. For this example, use $7,500 per month for assisted living.
Set your premium and multiplier. Assume a $100,000 premium with a 2.5x multiplier, creating a $250,000 benefit pool.
Apply the monthly cap. Many contracts cap monthly LTC payments. Assume a $5,000 monthly cap.
Calculate raw months of coverage. $250,000 ÷ $5,000 = 50 months, or roughly 4 years and 2 months.
Account for the elimination period. A 90-day elimination period means 3 months of out-of-pocket costs before benefits start. At $7,500/month, that’s $22,500 you cover directly.
Factor in inflation. Without an inflation rider, that $5,000 monthly cap buys less care each year. With a 3% compound rider, the cap grows to roughly $6,720 after 10 years, extending effective coverage.
Assumptions table:
Assumption | Value used |
Initial premium | $100,000 |
Benefit multiplier | 2.5x |
Total benefit pool | $250,000 |
Monthly benefit cap | $5,000 |
Local monthly care cost | $7,500 |
Elimination period | 90 days |
Inflation rider | 3% compound |
The benefit pool lasts roughly 50 months before exhaustion. If your priority is covering the full cost for a shorter period, you’d need either a higher monthly cap or a larger premium. If your priority is stretching coverage over five-plus years, a lower cap with the inflation rider is the better structure.
The practical takeaway from Fidelity’s cost-and-options overview is to compare effective months of coverage rather than just the multiplier number, because local care costs vary enough to make the same multiplier look very different in rural Iowa versus suburban New Jersey.
How to compare offers and what to ask insurers or agents
A structured approach to comparing proposals saves time and prevents you from choosing the contract with the best-looking headline number rather than the best actual coverage.
Sequential checklist for comparing proposals:
Confirm the funding source. Non-qualified lump sum, 1035 exchange, or qualified account? The answer changes the tax picture before you evaluate anything else.
Record the multiplier and benefit pool. Get the exact dollar amount, not just the ratio.
Note the monthly benefit cap. Divide the benefit pool by the cap to get raw months of coverage.
Check the elimination period. 30, 60, or 90 days? Calculate your out-of-pocket exposure.
Evaluate the inflation rider. Simple or compound? At what percentage? Run the 10-year and 20-year benefit value.
Review the surrender schedule. How many years, and what’s the year-one charge? What’s the free-withdrawal provision?
Confirm the death benefit. Is it the full account value, a guaranteed minimum, or something else?
Ask about the benefit trigger definitions. Get the exact ADL count and cognitive impairment standard in writing.
Questions to ask the agent or insurer:
Is this contract partnership-qualified in my state?
Can I change the monthly benefit cap after issue?
What happens to the benefit pool if I surrender the contract in year five?
Is the inflation rider available at any age, or does it phase out above a certain age?
What is the carrier’s financial strength rating (A.M. Best, Moody’s)?
When you’re ready to request illustrations, East Two West’s quote tool lets you compare offers from multiple carriers without a sales call if you prefer to start on your own. For a side-by-side look at annuity structures before you get to the LTC-specific layer, the SPIA vs. MYGA comparison is a useful primer on how income annuity mechanics differ.
Pro Tip: Ask for the “in-force illustration” at year 10 and year 20, not just the current benefit values. Carriers are required to provide these projections, and they reveal how the inflation rider and account crediting interact over time. A contract that looks competitive today may fall behind a competitor’s at year 15.
Common pitfalls and red flags when shopping for LTC annuities
Most problems with LTC annuities don’t show up in the sales presentation. They show up in the contract language, years later, when a claim is filed.
Red flags to watch for:
Vague inflation language. “Benefit increases may apply” is not the same as a guaranteed compound inflation rider. Get the exact percentage and compounding method in writing.
Long surrender schedules with no free-withdrawal provision. A 10-year surrender schedule with no annual free withdrawal is a liquidity trap. Most reputable contracts allow at least 10% per year penalty-free.
Indexed-crediting complexity without a clear floor. Some hybrid annuities credit interest based on an index (like the S&P 500) with a cap and floor. If the floor is 0%, your account value doesn’t grow in a flat market, which compresses the benefit pool’s real value over time.
Ambiguous caregiver payment rules. Some contracts exclude benefits when care is provided by a family member. Others allow it. This distinction matters enormously if informal family care is part of your plan.
Narrow benefit triggers. A contract that requires three ADL deficits instead of two is meaningfully harder to trigger. Read the exact language, not the summary.
No non-forfeiture option. If you stop paying (on a periodic-premium product) or surrender early, a non-forfeiture benefit preserves some coverage. Its absence is a red flag on any product with ongoing premiums.
On claim denials: The most common reasons LTC claims are denied or delayed are incomplete medical documentation, care provided in a setting not covered by the contract (some contracts exclude home care or adult day care), and failure to satisfy the elimination period properly. Confirm in writing which care settings qualify and what documentation the carrier requires before a claim is filed.
An editorial perspective on LTC annuities and what most buyers miss
The conventional wisdom around LTC annuities tends to frame the decision as “hybrid vs. standalone,” as if the two products are competing for the same buyer. They mostly aren’t. The buyer who benefits most from an LTC annuity is not the person who needs maximum care coverage at the lowest possible cost per benefit dollar. That person should look at standalone LTC insurance, if they can qualify. The LTC annuity buyer is the person who has a lump sum sitting in a low-yield account, wants to do something productive with it, and would rather not write an annual insurance check that disappears if they stay healthy.
What most buyers underestimate is the inflation rider decision. It’s easy to skip the compound inflation rider to lower the cost or increase the multiplier, and the short-term math makes that look smart. But care costs have historically risen faster than general inflation, and a benefit pool that looked adequate at 65 can look thin at 82. The difference between a simple and compound rider over 20 years is not marginal. It’s the difference between a benefit that keeps pace with care costs and one that covers an ever-shrinking fraction of the bill.
The other thing worth saying plainly: the multiplier is a marketing number. What actually matters is the monthly benefit cap relative to your local care cost, the elimination period you can afford to self-fund, and whether the inflation rider is compound. Run those three numbers before you look at anything else on the illustration.
Get a fast, no-pressure LTC annuity quote through East Two West
Comparing LTC annuity offers across carriers is where most buyers get stuck. The illustrations look different, the multipliers aren’t directly comparable, and it’s hard to know whether you’re looking at a genuinely better product or just a better-presented one.
[
East Two West is an independent insurance practice that pulls quotes from multiple carriers, so you see competing offers side by side without a single carrier’s agent steering the conversation. If you prefer to start on your own, the online quote tool lets you enter your age, premium amount, and funding source and get initial figures without a call. If your situation is more complex, a personalized consultation walks through the multiplier, monthly cap, inflation rider, and surrender schedule across the carriers that make sense for your profile. Either way, you get honest guidance and only move forward if the numbers actually work for your plan. Compare your options at East Two West and request an illustration from the carriers that fit your situation.
Primary sources and further reading
NAIC Shopper’s Guide to Long-Term Care: Covers LTC insurance and hybrid product structures, benefit triggers, and consumer rights.
ACL — Annuities for Long-Term Care: Federal guidance on immediate and deferred annuity structures for LTC funding and Medicaid interaction.
ACL — Costs of Care: Regional care cost data useful for sizing your coverage need.
IRS Private Letter Ruling 0919011: Tax precedent for annuity/LTC distributions and exchanges; consult a tax advisor for your specific situation.
Fidelity — Long-Term Care Costs and Options: Practical overview of hybrid annuity mechanics and benefit pool multipliers.
My Annuity Doctor — Annuities for Long-Term Care: Detailed explanation of LTC rider types, hybrid products, and Pension Protection Act tax treatment.
SSA Long-Term Care FAQ: Confirms Medicare’s limited LTC coverage and the role of private planning.
This article is general educational information, not tax, legal, or financial advice. Confirm current rules and contract terms with a licensed tax advisor, attorney, and the issuing carrier before making any purchase decision.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
Recommended
Comments