U.S. Seniors: 5 Life Insurance Types to Buy or Skip
Most seniors with a spouse, small debts, or a funeral to plan for should get covered now, and a final-expense or simplified-issue policy is the fastest, most affordable path for most budgets. The exception is someone with no dependents and a fully funded funeral plan already in place. Either way, run a quick comparison across carriers before you sign anything. A licensed broker like East Two West can pull multiple quotes at once and walk you through which underwriting path fits your health picture.
TL;DR:
Most seniors should compare multiple carriers before purchasing final expense or simplified-issue policies, as pricing differences grow significantly after age 70.
Term policies are the cheapest for those with a specific debt or mortgage to cover but often become unavailable after age 75 or 80, and premiums increase sharply with age.
Whole life policies provide permanent death benefits and cash value but are more expensive; they are suitable for seniors seeking a legacy or long-term cash strategy.
Guaranteed-issue policies accept nearly everyone within 50 to 85 years old but have a graded death benefit period, making them less ideal if natural death occurs within the first two years.
Premiums for a $100,000 policy vary based on health and carrier, with healthy seniors paying lower rates and full underwriting generally yielding the best prices at larger coverage amounts.
Table of Contents
Life Insurance for Seniors: Which Type Actually Fits Your Situation
The policy type matters more than the carrier for most seniors. Five product categories cover nearly every situation you’ll run into after age 60, and each one solves a different problem.
Term life insurance pays a death benefit only if you die during a set period, usually 10, 15, or 20 years. It’s the cheapest way to buy a large amount of coverage, but most carriers stop issuing new term policies to applicants past 75 or 80, and premiums for a 65 year old buying term run several times what a 45 year old pays for the same face amount. Term makes sense if you still have a mortgage, a working spouse who depends on your income, or a specific debt you want covered for a defined stretch of years.
Whole life insurance builds cash value alongside a permanent death benefit that never expires as long as premiums get paid. It costs more than term for the same coverage amount, but the price locks in and the policy accumulates value you can borrow against later. Whole life fits seniors who want a permanent legacy benefit or who are using the policy as part of a longer-term cash-value strategy rather than pure death-benefit protection.
Final expense (burial) insurance is a small permanent policy, built specifically to cover typical funeral costs, outstanding medical bills, and small debts. Underwriting is simplified or guaranteed, approval often takes days rather than weeks, and this is the single most common product seniors actually buy.
Simplified-issue policies skip the medical exam but still ask health questions on the application. You’ll get a faster decision than full underwriting, and pricing lands between guaranteed-issue and fully underwritten policies. This works well if you’re in reasonably good health but want to avoid blood work and a paramedical exam.
Guaranteed-issue policies ask no health questions at all and accept nearly every applicant within the age range, usually 50 to 85. The trade-off is a graded benefit period, meaning the full death benefit doesn’t kick in until the policy has been active for two or three years. If you have serious health conditions that would disqualify you elsewhere, this is often the only door left open.
A few practical trade-offs to weigh:
Term costs the least per dollar of coverage but disappears when the term ends.
Whole life costs more but never expires and builds equity.
Final expense and simplified-issue split the difference for smaller amounts.
Guaranteed-issue costs the most per dollar of actual payout, especially in the early years.
Seniors who want a permanent policy with growth potential sometimes look at indexed universal life insurance instead of traditional whole life, though it carries more moving parts and works better for those still accumulating wealth than those purely focused on final expenses.
Who Qualifies for Coverage and What Underwriting Looks Like
Age alone rarely disqualifies you, but it does narrow your options. Here’s how the underwriting landscape typically breaks down by product:
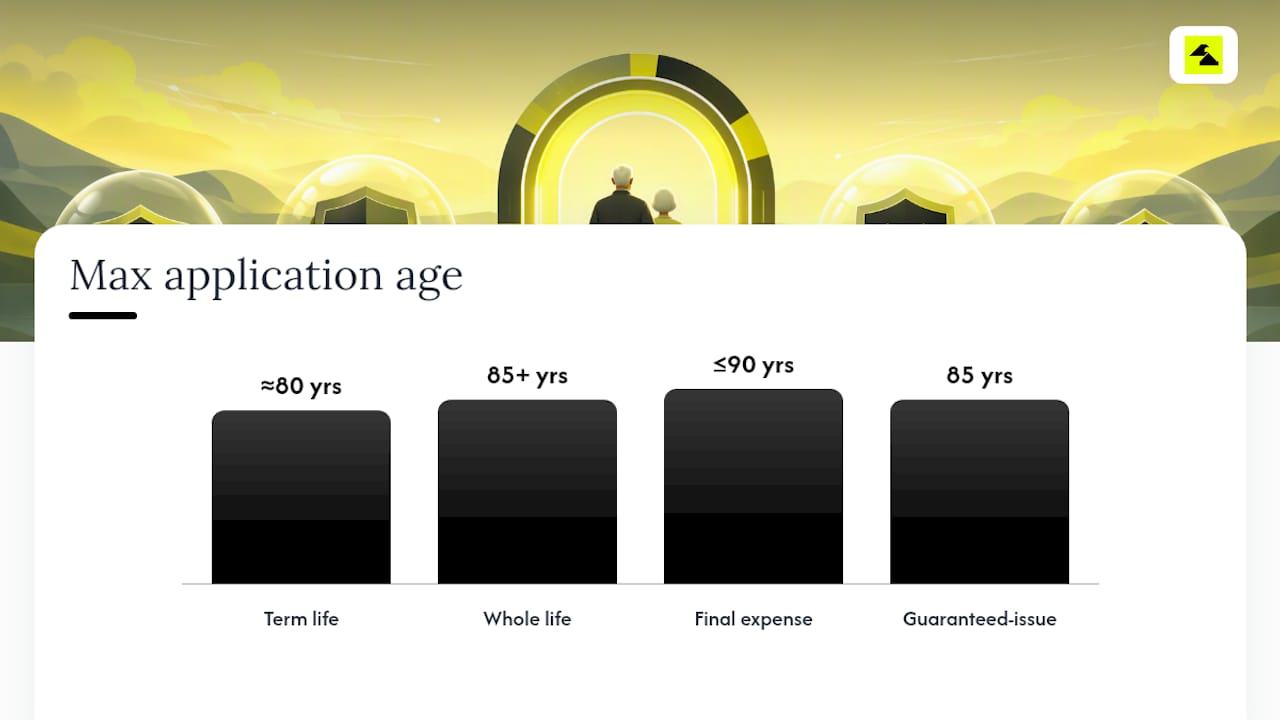
Term life usually caps new applications around age 75 to 80, and the healthiest applicants get the best rates.
Whole life stays available later, often to 85 or beyond, though premiums climb steeply with age.
Final expense policies commonly accept applicants from 50 up to 85, sometimes 90, with simplified health questions.
Guaranteed-issue policies exist specifically for the 50 to 85 range and accept applicants regardless of health history, subject to the graded-benefit waiting period.
Health conditions and prescription history shape both approval odds and pricing far more than age by itself. Insurers pull prescription drug databases and medical records during underwriting, and conditions like diabetes, heart disease, or recent cancer treatment can push you from standard rates into substandard tiers or toward guaranteed-issue products. This is exactly why comparing carriers pays off. Cost differences between insurers grow substantially once applicants pass 70, since each company weighs the same health history differently, according to MoneyGeek’s life insurance data.
Three underwriting paths exist, and understanding which one you’re on changes what to expect:
No-exam underwriting relies on application answers, prescription records, and database checks. Decisions often come back in days.
Accelerated underwriting uses similar data sources plus predictive scoring to approve healthy applicants without a paramedical exam, and East Two West’s accelerated underwriting guide breaks down exactly which applicants tend to qualify.
Full underwriting includes a medical exam, blood and urine work, and a complete records review, usually taking two to six weeks but often producing the lowest premiums for healthy applicants.
Guaranteed-issue policies carry one more wrinkle: a graded-benefit period. If death occurs from natural causes within the first two or three years, the insurer typically refunds premiums paid plus interest instead of paying the full face amount. Accidental death is usually covered at full value from day one. It’s not a reason to avoid these policies, but it’s a detail too many buyers miss until a claim is filed.
Many seniors assume health issues disqualify them entirely, but Forbes Advisor’s analysis of senior life insurance points out that the range of product structures, from underwritten term to guaranteed-issue, means some coverage exists for nearly everyone willing to shop around.
How Much Does Life Insurance Cost for Seniors?
Four factors drive your premium more than anything else: age, smoker status, benefit amount, and policy type. A 65 year old nonsmoker pays a fraction of what a 65 year old smoker pays for the same coverage, and every five years of age typically adds a meaningful percentage to the premium on permanent products.
For a small final-expense policy in the $10,000 to $25,000 range, expect monthly premiums generally ranging from modest to moderate amounts depending heavily on health and carrier.
Guaranteed-issue versions of these amounts run higher than simplified-issue, sometimes by 20 to 40%, because the insurer takes on more risk.
Larger policies come with a different set of qualifiers. A $100,000 term policy for a healthy 65 year old typically costs substantially less per month than a permanent policy with the same face amount, as the latter covers lifelong protection. A $500,000 policy for a 70 year old man typically requires full underwriting, including a medical exam, with premiums varying significantly based on health rating and insurer.
Pro Tip: Before buying a final-expense policy, add up the total premiums you’d pay over 10, 15, and 20 years and compare that total to the death benefit. If you’re likely to pay more in premiums than the policy pays out before you reach average life expectancy, a savings account earmarked for funeral costs might serve you better.
The scale of the U.S. life insurance market backs up why this comparison shopping matters. Individual life insurance makes up the majority of coverage in force nationwide, and insurers pay out billions in claims annually, according to the ACLI’s 2025 Life Insurers Fact Book. That scale means real competition exists between carriers for your business, even at 70 or 75. Funeral costs themselves also give useful context for sizing a policy. The National Funeral Directors Association tracks funeral expenses that regularly justify the $10,000 to $15,000 range many seniors target for burial coverage.
Choosing the Right Policy: A Practical Decision Framework
Start with the need, not the product. Are you covering a funeral and small debts? Replacing income for a surviving spouse? Leaving a legacy gift? Each answer points toward a different product category before you even look at price.
Once the need is clear, set a monthly budget you can sustain for decades, not just this year. A policy you let lapse in year eight because the premium became unaffordable is worse than never buying one, since you’ll have paid years of premiums for nothing. From there, match the need and budget to a product type using the categories covered earlier, then decide which underwriting path fits your health situation.
When comparing actual offers, weigh these criteria against each other rather than focusing on price alone:
Premium stability: does the rate increase over time, or is it level for life?
Waiting periods: does a graded-benefit clause apply, and for how long?
Riders available: does the policy include an accelerated death benefit rider, which lets you access part of the death benefit early if diagnosed with a terminal illness?
Exclusions: are there specific causes of death or activities excluded from coverage?
Company financial strength: does the insurer carry solid ratings from independent agencies?
Claims-paying history: does the company have a track record of paying claims promptly without excessive disputes?
Ask any agent or online quote tool these exact questions before signing anything: What’s my rate class, and why? Does this premium ever increase? What exactly triggers the graded-benefit period, and when does it end? Is there an accelerated death benefit rider, and does it cost extra? What happens if I miss a payment?
Watch for a few red flags. High-pressure tactics that push you to decide same-day are a warning sign, as are vague answers about waiting periods or a premium-to-benefit ratio that seems disconnected from your health and age. If an agent can’t clearly explain why you’re being quoted a specific rate class, that’s worth pushing back on.
Buying direct online works fine for straightforward cases, healthy applicants wanting a simple final-expense policy. A licensed advisor earns their place when your health history is complicated, when you’re comparing permanent versus term for a larger amount, or when you want someone to actually shop the market instead of pitching one company’s product. Long-term care needs sometimes factor into this decision too, and understanding how long-term care insurance interacts with a living-benefit rider can change which policy makes the most sense.
Applying for Coverage: What to Expect Step by Step
The application process looks different depending on which underwriting path you’re on, but the general sequence stays consistent.
Gather your information first. You’ll need a list of current medications, dosages, and prescribing doctors, plus basic health history including any diagnoses in the last five years.
Get quotes from multiple carriers. This is where working with a broker saves real time, since a single application to a broker can generate quotes across dozens of insurers instead of one at a time.
Submit the application. Answer health questions honestly. Misrepresenting a condition can void a claim later, which defeats the entire purpose of buying coverage.
Underwriting review happens. No-exam and accelerated paths often return decisions in 24 hours to a few days. Full underwriting with a medical exam typically takes two to six weeks.
Policy issue and delivery. Once approved, you’ll receive the policy documents, and coverage begins once the first premium is paid.
A large share of consumers now start this process online. LIMRA’s 2025 research found that 92% of consumers research life insurance online, and roughly a quarter say they’d complete the entire purchase digitally. That research phase is smart, but pairing it with a licensed broker who can compare actual quotes tends to produce better outcomes than researching alone and applying to a single carrier.
If you’re relatively healthy and want the lowest possible premium on a larger policy, a medical exam is often worth the wait. Full underwriting rewards good health with meaningfully better rates than no-exam products, so don’t assume skipping the exam always saves money. It sometimes costs you the best rate class available.
Behind This Guide: Who Wrote It and Who Backs It
This guide comes from Jib Hunt at East Two West, whose work focuses on whole life design and the Infinite Banking Concept, helping clients understand how properly structured permanent insurance can build liquidity and control beyond a simple death benefit.
East Two West works with individuals, families, and business owners across the United States, comparing term, whole life, final expense, guaranteed-issue, and indexed universal life policies across multiple carriers rather than pushing a single company’s product. That structure matters for seniors specifically, since carrier pricing diverges the most at older ages, and a broker who isn’t tied to one insurer can actually shop the difference.
[Case studies and client testimonials to be added.]
This guide reflects general information for U.S. residents and shouldn’t replace a conversation with a licensed insurance agent about your specific health history and financial goals.
Why Most Senior Life Insurance Advice Misses the Point
The standard advice online tells seniors to “compare quotes” and “know your budget,” which is technically true and practically useless. The real failure point isn’t a lack of information. It’s that most seniors either overbuy permanent coverage they can’t sustain for 20 years, or underbuy because they assume final expense is the only option available to them.
The math matters more than the product category. A guaranteed-issue policy makes sense for someone with serious health conditions, but it’s a poor fit for someone who’d actually qualify for cheaper simplified-issue coverage and just never checked. That’s the gap East Two West’s model is built to close: pulling quotes across carriers instead of guessing which company might say yes.
If you take one thing from this guide, run the break-even math before you sign anything, and get more than one quote before assuming guaranteed-issue is your only door. Most seniors have more options than they think.
— Jib Hunt
Get a Personalized Life Insurance Quote
East Two West gives you one place to compare final-expense, term, whole life, and guaranteed-issue quotes across dozens of carriers instead of calling insurers one by one or accepting the first offer you see. That matters most for seniors, since pricing gaps between companies widen the most after 70, and a single-carrier quote rarely tells you whether you’re getting a fair rate.
[
Getting started takes a few minutes. Head to the East Two West quote page with your age, general health history, current medications, and target coverage amount ready, and you’ll get matched with quotes suited to your situation. A phone consultation walks you through multiple carrier options, explains which underwriting path fits your health picture, no-exam, accelerated, or full underwriting, and answers questions about riders like the accelerated death benefit before you commit to anything. There’s no obligation to buy, and no pressure to decide on the call.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
FAQ
Is It Worth Getting Life Insurance at 70 Years Old?
Yes, for most seniors with a spouse, small debts, or funeral costs to cover. Final-expense and simplified-issue policies remain available well into the 70s and 80s, and premium differences between carriers widen significantly at this age, making it worth comparing quotes rather than accepting the first offer.
How Much Does a $100,000 Life Insurance Policy Cost for Seniors?
A $100,000 term policy for a healthy 65 year old typically costs substantially less per month than a permanent policy with the same face amount, as the latter covers lifelong protection. Exact pricing depends heavily on health rating, smoker status, and which carrier you choose.
How Much Is a $500,000 Life Insurance Policy for a 70 Year Old Man?
A $500,000 policy for a 70 year old man typically requires full underwriting, including a medical exam, with premiums varying significantly based on health rating and insurer. Comparing multiple insurers matters most at this coverage level, since pricing gaps between companies grow substantially after 70.
What Is the Best Life Insurance for Seniors Over 80?
Guaranteed-issue and simplified-issue final-expense policies are typically the most accessible options for seniors over 80, since many term and full-underwriting products stop accepting new applicants past that age. A broker who compares multiple carriers, like East Two West, can identify which insurers still offer competitive rates in this age bracket.
Recommended
Comments